Form 8857 Guide
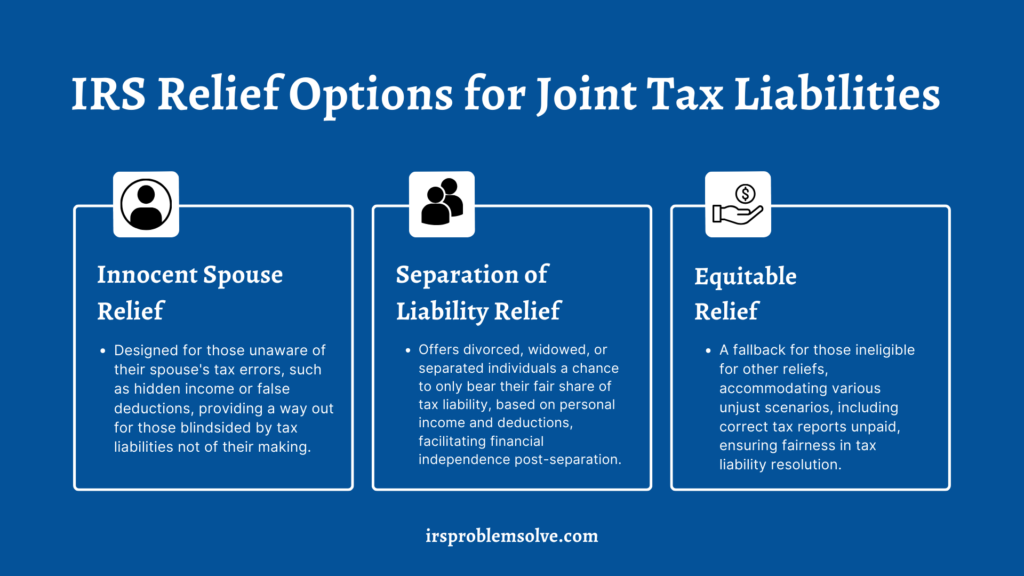
Form 8857 asks the IRS to consider relief from certain tax liabilities involving a spouse or former spouse. Completing it requires more than selecting a relief category; the IRS needs the correct tax years, relevant history, and facts supporting the request.
For an explanation of the different relief types and who may qualify, read our innocent spouse relief overview. This guide focuses on preparing and submitting the request.
Form 8857 Is More Than a Checkbox Form
Form 8857 is the IRS form used to request innocent spouse relief, separation-of-liability relief, or equitable relief. The IRS uses the answers on the form, together with supporting records and any additional explanation, to decide whether relief is available.
That means the quality of the factual presentation matters. A short statement such as “my former spouse caused the problem” may be true, but it does not explain what happened, what you knew, when you learned about the liability, or why the requested relief should apply.
A stronger submission connects the tax years, return history, household or business facts, IRS notices, and supporting records into a clear timeline.
Start With the Correct Tax Years
Identify the years of the liability for which you are requesting relief. A refund applied from another year does not necessarily make that refund year the year that belongs on the request.
For example, suppose the IRS used a 2025 refund to pay part of a joint liability from 2022. The refund year and the disputed tax year are different. The Form 8857 request should identify the year or years connected to the liability for which relief is being requested.
Review the IRS account history and follow the current form instructions when identifying the relevant periods.
What Form 8857 Asks You to Explain
The form covers several areas. Prepare the information for each tax year involved, and explain when the facts changed from one year to another.
| Area | Information to Prepare |
|---|---|
| Eligibility and tax years | Why the form applies and which liabilities or tax years are involved. |
| Personal and marital information | Safe contact details, marital status, dates, education, and relevant health information. |
| Returns and household finances | Your involvement, what you knew, how payments were expected to be made, and relevant transfers. |
| Current finances | Assets, household income, expenses, and people you support. |
| Abuse or financial control | Relevant circumstances you choose to provide and the effect those circumstances had on your ability to question or control the tax matter. |
| Additional facts | Important information not adequately addressed elsewhere on the form. |
| Refund request and signature | Whether you request a qualifying refund or credit and complete the signature section. |
Use the current form and current instructions.
Form wording and submission details can change, so do not rely on an old saved copy without checking the IRS version first.
Build a Timeline, Not Just a Conclusion
A statement that the tax is “my former spouse’s responsibility” does not explain what actually happened.
Organize the account chronologically: when the return was prepared, your involvement in the return, what you understood about the income or payments, when you first learned about the problem, what the IRS did afterward, and how the circumstances changed over time.
Match supporting records to the statements they support. Depending on the circumstances, useful evidence may include tax returns, IRS correspondence, bank records, payroll or business records, divorce documents, communications, payment records, or other financial information.
Clearly distinguish facts you know from information you do not have. Do not guess at an answer merely to fill a blank.
Explain What You Knew (and What You Did Not Know)
Knowledge is often one of the most important factual issues in a spouse-relief request. The IRS may look beyond whether you understood tax law and instead focus on what you knew about the underlying income, deductions, payments, household finances, business activity, or accounts.
If the facts differed by year, say so. A person may have had access to records in one year but not another, or may have learned about a business problem only after an audit began.
Address Questions About the Joint Return Carefully
Form 8857 asks questions about whether the taxpayer intended to file jointly. That issue deserves careful attention.
Forgery, duress, coercion, or another dispute about whether a valid joint return was ever filed may raise a legal issue that is different from the ordinary spouse-relief analysis.
Do not treat the joint-return question as a routine checkbox if the facts are disputed. Review what was signed, how the return was filed, what you understood at the time, and whether you actually consented to filing jointly.
Abuse, Coercion, and Financial Control
Abuse, threats, coercion, fear, or financial control may affect how the IRS evaluates a spouse-relief request. These facts can help explain why a taxpayer did not challenge a return, did not have access to information, or did not understand what was happening with the household finances.
The goal is not to provide every traumatic detail possible. The goal is to explain the facts that are relevant to the tax issue and the IRS analysis.
Organize sensitive supporting material carefully, and consider privacy and safety before submitting documents that include a current address, workplace information, medical information, or other personal details.
Your Spouse or Former Spouse Will Be Notified
The IRS generally gives the other spouse or former spouse an opportunity to participate in the review process. This applies even when the request involves abuse or another difficult relationship history.
The IRS protects specified personal information, but information relevant to deciding the request may still become part of the administrative process.
Raise safety and privacy concerns before filing.
Think about how supporting evidence can establish the relevant facts without unnecessarily exposing current personal details.
Be Consistent When Reporting Current Financial Information
Form 8857 asks for current financial information because financial hardship and household circumstances may matter in some requests.
Review income, assets, household expenses, people supported, and other financial information for consistency. If an amount varies from month to month, explain that rather than forcing an inaccurate fixed number.
Do not treat this section as interchangeable with an IRS collection financial statement such as Form 433. Form 8857 has its own purpose and asks questions in the context of spouse relief.
Check Submission Instructions and Separate Deadlines
Do not attach Form 8857 to your federal income tax return. Follow the current IRS instructions for where and how to submit the form and attachments.
Keep a complete copy of the packet, including attachments, and retain evidence of when and how you submitted it.
Filing Form 8857 does not replace every other tax deadline. For example, if you have received a notice of deficiency, the IRS instructions explain that you should separately protect the deadline for filing a Tax Court petition rather than assuming Form 8857 extends that period.
Review every outstanding IRS notice separately.
An innocent-spouse request may be important, but it does not automatically preserve unrelated audit, appeal, deficiency, collection, or Tax Court rights.
What Happens After Filing Form 8857?
The IRS reviews the request and may ask for additional information. The other or former spouse generally has an opportunity to participate.
The IRS states that review may take six months or longer. That makes recordkeeping important: keep copies of every submission, new IRS letter, response, and delivery confirmation.
The IRS may issue a preliminary determination, and appeal rights can apply. A requesting spouse may also have Tax Court review rights after a final determination, or in certain circumstances if the IRS has not issued a final determination within six months.
Read each new letter promptly. A new IRS decision can create a new deadline even if the original Form 8857 request was timely.
Common Problems to Avoid When Preparing the Request
Current IRS Form 8857 Resources
Use the current IRS materials when preparing the request:
Help Reviewing a Form 8857 Request
Some requests involve a straightforward joint tax problem. Others involve several years, business income, disputed returns, divorce litigation, hidden accounts, abuse, financial control, active collection, or a spouse who is likely to contest the facts.
Todd S. Unger can review the tax years involved, filing history, timing concerns, supporting records, and the factual explanation before submitting a Form 8857 request.
For representation information, visit the firm’s innocent spouse relief attorney page.
Have Questions About a Form 8857 Request?
Contact Todd S. Unger’s office to discuss the tax years, IRS notices, filing deadline, and information needed to review the request.
Do not send a completed Form 8857, Social Security numbers, account numbers, or sensitive attachments through the initial website contact form.
