Is an IRS Offer in Compromise Right for You?
An Offer in Compromise can settle certain IRS tax liabilities for less than the full amount owed, but it is not simply a request to pay less. The IRS looks at why the offer is being made, whether the taxpayer is eligible, and whether collectibility is the issue, based on income, expenses, assets, and ability to pay.
Before preparing an offer, determine whether the tax itself is correct, whether it can realistically be paid through another collection option, and whether the financial information supports the proposed compromise.
What an Offer in Compromise Actually Does
An Offer in Compromise is an agreement between a taxpayer and the IRS to resolve eligible tax liabilities for an agreed amount. The IRS may consider an offer when there is doubt about collectibility, doubt about the underlying liability, or when compromise would promote effective tax administration.
The important point is that these are different legal and procedural grounds. A taxpayer who agrees with the tax but cannot pay it in full is not presenting the same case as someone who believes the assessment itself is wrong.
Make that distinction before completing the application.
First Question: Do You Agree With the Tax?
You Agree the Tax Is Owed
The question becomes whether the IRS could collect the full amount and whether an Offer in Compromise is more appropriate than an installment agreement, hardship status, or another collection alternative.
You Dispute the Tax
A Doubt as to Liability offer may be relevant when there is a genuine dispute about whether the tax is owed or the amount is correct. This uses a different form and does not rely on the same financial analysis as a collectibility offer.
Do not use a collectibility offer to solve a liability dispute without first identifying the actual issue.
Audit reconsideration, administrative appeals, refund procedures, or another dispute process may sometimes be more appropriate.
The Three Main Bases for an Offer in Compromise
Doubt as to Collectibility
The taxpayer agrees that the liability is correct, but the IRS is unlikely to collect the full amount through available assets and future income during the collection period.
Effective Tax Administration
The tax is correct and could potentially be collected in full, but full collection may create qualifying economic hardship or exceptional public-policy or equity concerns.
Doubt as to Liability
There is a genuine dispute about whether the assessed tax is legally owed or whether the amount is correct.
Basic Eligibility Comes Before the Offer Amount
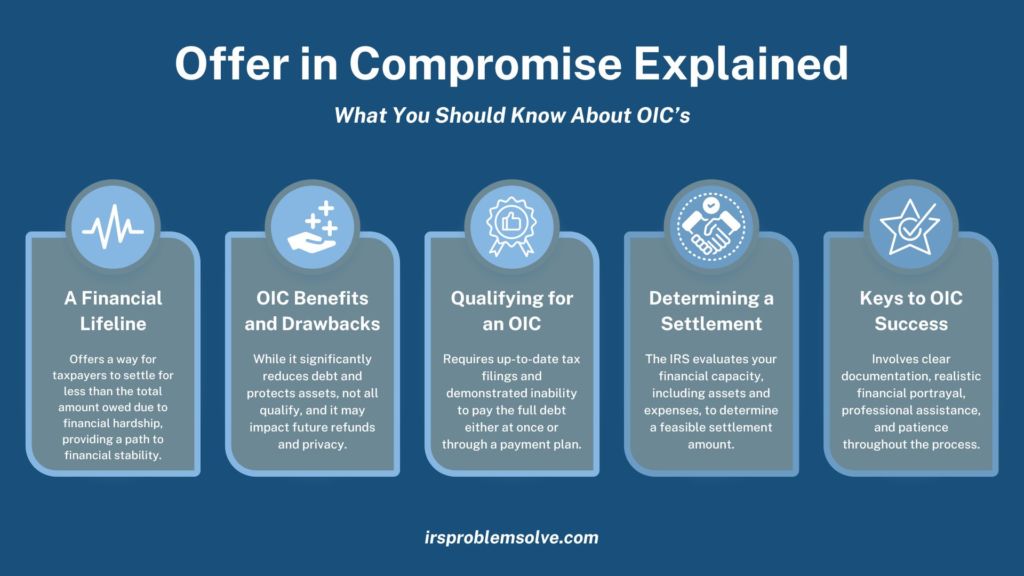
For most collectibility and effective-tax-administration offers, the taxpayer must be current with required filing and payment obligations before the IRS will consider the offer.
The IRS provides an Offer in Compromise Pre-Qualifier Tool for a preliminary review, although a pre-qualifier result does not guarantee acceptance.
How the IRS Evaluates a Collectibility Offer
The IRS does not automatically accept a standard percentage of the tax debt. For a Doubt as to Collectibility offer, the analysis generally centers on what the IRS believes it could reasonably collect from available assets and future income.
That analysis is often referred to as reasonable collection potential. It can include bank accounts, investments, real estate equity, vehicles, business assets, future disposable income, and other financial resources.
The IRS also evaluates allowable living expenses. The IRS does not automatically accept actual household spending just because the taxpayer currently pays it. National and local collection standards can affect how certain expenses are treated.
The tax balance itself does not determine the offer amount.
Two taxpayers who owe the same amount can have very different OIC results because their assets, income, expenses, and collection potential are different.
Use the OIC-Specific Financial Forms
A common mistake is using ordinary collection financial statements instead of the forms designed specifically for an Offer in Compromise.
Individuals and Sole Proprietors
Use Form 433-A (OIC) when required for an individual, wage earner, self-employed taxpayer, or sole proprietor.
Businesses
Use Form 433-B (OIC) when required for a corporation, partnership, LLC, or other business entity.
For Doubt as to Collectibility and Effective Tax Administration offers, the current Form 656-B Offer in Compromise Booklet contains Form 656 and the OIC-specific financial statements.
Doubt as to Liability Uses a Different Form
If the dispute is about whether the tax is actually owed, the IRS uses Form 656-L, Offer in Compromise (Doubt as to Liability).
A doubt-as-to-liability offer generally requires a written explanation and supporting evidence showing why the liability is incorrect. It does not use Form 433-A (OIC) or Form 433-B (OIC), and the IRS does not require an application fee or offer payment with a Doubt as to Liability submission.
Advantages and Tradeoffs of an Offer in Compromise
Potential Advantages
- Can resolve eligible tax liabilities for less than the full assessed balance.
- Can provide a defined path to closing a long-running collection matter.
- IRS levy activity is generally restricted while a processable offer is pending, subject to statutory exceptions.
- Provides appeal rights if the IRS formally rejects the offer.
Important Tradeoffs
- Requires detailed financial disclosure for collectibility and ETA offers.
- The IRS can request additional records and verify financial information.
- The collection statute is generally suspended while the offer is pending.
- Offer payments generally are not returned if the offer is withdrawn, rejected, or returned after processing.
- The taxpayer must comply with the accepted offer terms and future filing/payment obligations.
OIC Payment Options Matter
The payment structure affects what must be submitted with the offer and how future income is used to calculate a minimum offer amount.
Lump Sum Offer
Generally requires a payment equal to 20% of the total offer with the application. If accepted, the remaining offer balance is paid in five or fewer payments within five or fewer months after acceptance.
Periodic Payment Offer
Generally requires the first proposed monthly payment with the application, followed by continuing monthly payments while the IRS evaluates the offer. The proposed payment period is generally six to 24 months.
Individual taxpayers who qualify under the IRS Low-Income Certification rules generally do not need to submit the application fee, initial payment, or monthly offer payments while the offer is under consideration.
Current Application Fee
The current IRS application fee for a standard Offer in Compromise is $205, unless an exception applies.
Qualifying individuals who meet the Low-Income Certification rules are exempt from the application fee and required offer payments during consideration. Doubt as to Liability offers also do not require the OIC application fee or an offer payment.
What Happens While the IRS Reviews the Offer?
Once the IRS accepts an offer for processing, it reviews the financial information and may request additional documentation, clarification, or updated records.
Levy activity is generally restricted while a processable offer is pending, and for a limited period after a rejection while appeal rights remain available. The IRS may still file a Notice of Federal Tax Lien while the offer is under review.
The legal period for collection is generally extended during the period the offer is pending. Existing installment-agreement payments generally do not have to continue while the offer is being evaluated, although required offer payments must continue when applicable.
If the IRS does not make a determination within the statutory two-year period, subject to the applicable rules and exclusions, the offer can be deemed accepted by law.
What Acceptance Does (and Does Not)
If the IRS accepts the offer, the taxpayer must pay the agreed amount according to the acceptance terms.
For Doubt as to Collectibility and Effective Tax Administration offers, the taxpayer generally must remain current with required federal tax returns and tax payments for five years after the acceptance date. Failure to satisfy the offer terms can cause the agreement to default.
If the IRS previously filed a Notice of Federal Tax Lien, the IRS generally releases the lien after the offer payment terms have been satisfied.
An accepted offer may also affect tax refunds or overpayments due for periods through the acceptance date under the terms of the agreement. That is different from saying that a taxpayer generally “loses tax credits.”
Do Not Judge Your Case by a National Acceptance Percentage
A general approval statistic does not tell you whether a particular offer is viable. Cases differ based on the legal basis for the offer, filing compliance, assets, income, allowable expenses, payment terms, supporting documentation, and whether the proposed amount matches the IRS financial analysis.
The better question is whether your case facts meet the requirements for the type of offer you’re submitting.
Compare an Offer With Other IRS Options
An Offer in Compromise is not automatically the best collection solution simply because it can reduce a balance.
May be more appropriate when you can pay the full balance over time without creating an unmanageable financial burden.
May be considered when paying the IRS would prevent the taxpayer from meeting necessary living expenses. The debt remains due, and interest and penalties generally continue to accrue.
If the balance is wrong, correcting the assessment may be more important than negotiating how to pay it.
May be relevant when a joint tax liability involves a spouse or former spouse and the spouse-relief requirements may apply.
What to Review Before Submitting an Offer
Base a collectibility offer on current, supportable financial information rather than estimates designed to produce a particular offer amount.
Transfers of assets, unusual withdrawals, loans to others, ownership interests, trusts, expected inheritances, and other financial interests may also need to be disclosed depending on the facts and the questions on the current OIC forms.
What if the IRS Rejects the Offer?
A formal rejection generally explains why the IRS declined the offer. The taxpayer may appeal the rejection to the IRS Independent Office of Appeals.
The IRS generally provides 30 days from the date of the rejection letter to request an appeal. Review the rejection letter promptly, rather than waiting until the end of that period, to decide how to respond.
Privacy and Accepted Offers
Certain information relating to accepted Offers in Compromise may be available through IRS public-inspection procedures. That is different from saying an OIC appears on a consumer credit report or automatically changes a credit score.
When an OIC Review May Be Worthwhile
An Offer in Compromise may deserve closer review when the tax balance is substantial, the taxpayer cannot realistically pay it in full during the collection period, asset equity is limited, or exceptional hardship circumstances affect the case.
It may be less appropriate when the IRS believes the taxpayer can fully pay through available assets or future income, required returns or deposits are not current, or the real issue is that the tax assessment itself is wrong.
Todd S. Unger can review the liability, collection status, financial information, and available IRS alternatives before preparing an offer.
Find Out Whether an Offer Makes Sense
Before committing to an Offer in Compromise, review the amount owed, tax periods, filing status, assets, income, expenses, and other collection options.
